Purchase Financing
Buying a Home? Let's Find the Right Financing for Your Purchase.
Whether you're buying your first home, moving into your next one, or purchasing an investment property, I'll help you explore mortgage options, understand the costs, and prepare for your purchase.
- Financing options from multiple lending sources.
- Guidance on monthly payments, down payments, and closing costs.
- Personalized support from our first conversation through closing.
- Mortgage Experience
- 10 Years4 Months
- Funded
- $100M+
Licensing and registration can be checked independently on NMLS Consumer Access.
- NMLS ID
- 1463508
- Company
- West Capital Lending, Inc. (1566096)
- Office
- 17911 Von Karman Avenue Suite 400, Irvine, CA 92614
- Licensed states
- CA, CO, FL, IA, MD, MO, OR, PA, TN, TX, VA, WA12 active state licenses/registrations
The Right Mortgage Starts With Your Situation.
Buying a property is about more than getting a loan approved. Your down payment, income, monthly obligations, available cash, and long-term plans all affect which financing options may fit.
I work with multiple lending sources to help you explore programs, understand the numbers, and prepare for your purchase.
Understand Your Purchasing Power
Review estimated financing, available funds, and monthly payment considerations.
Explore Available Mortgage Options
Compare relevant loan programs and requirements based on the purchase and the borrower's financial circumstances.
Prepare for the Next Step
Understand documentation, pre-approval requirements, important dates, and what happens between application and closing.
Where Are You in the Buying Process?
Choose the option that fits. I'll carry that answer into the purchase inquiry so you do not have to select it again.
How the Purchase Process Works
An inquiry does not guarantee financing, pre-approval, or closing.
Experience With Different Purchase Scenarios
Eligibility, available programs, documentation, loan terms, and requirements vary by lender, property, and borrower. Not every program is available in every situation.
I work with multiple lending sources, including a network of 150+ lender partners used across the practice, to review purchase scenarios that may include:
Conventional home purchases
Primary-residence financing when the property, credit, income, and down payment fit conventional guidelines.
Jumbo financing
Purchase amounts above conforming loan limits, subject to lender overlays and qualification.
Investment-property purchases
Financing that may consider rental income, reserves, and occupancy, depending on the program.
Self-employed borrowers
Situations where tax returns, business income, or bank statements may be reviewed in different ways.
Alternative income-documentation scenarios
Programs that document income differently than a standard W-2 file, when the lender allows it.
More complex financing situations
Files that need a closer look because the property, credit, or income does not fit a single template.
Educational Overview
What Will Your Purchase Actually Cost?
Evaluating financing involves more than comparing interest rates. A purchase typically includes the monthly payment, cash to close, and third-party charges that I do not independently set.
Principal and interest
The loan payment itself, based on the amount financed, term, and the rate a lender may offer if you qualify.
Property taxes and homeowners insurance
Often collected in an escrow account and included in the total monthly housing payment.
Mortgage insurance, when applicable
May apply depending on down payment, occupancy, loan program, and lender guidelines.
HOA dues, when applicable
Community or condominium dues are separate from the mortgage and still affect monthly housing cost.
Closing costs and prepaid expenses
May include appraisal, title, escrow or settlement, recording, credit report, prepaid taxes, and insurance.
I can explain company charges within the applicable lending arrangement. I do not independently set fees charged by appraisers, title companies, escrow companies, government agencies, or other third parties.
Informal estimates are educational only. They are not lender quotes and are not substitutes for a Loan Estimate or Closing Disclosure, which provide required cost figures as an application progresses.
If you want a simple educational payment illustration, you can Open the educational payment calculator. Hypothetical figures are not lender quotes.
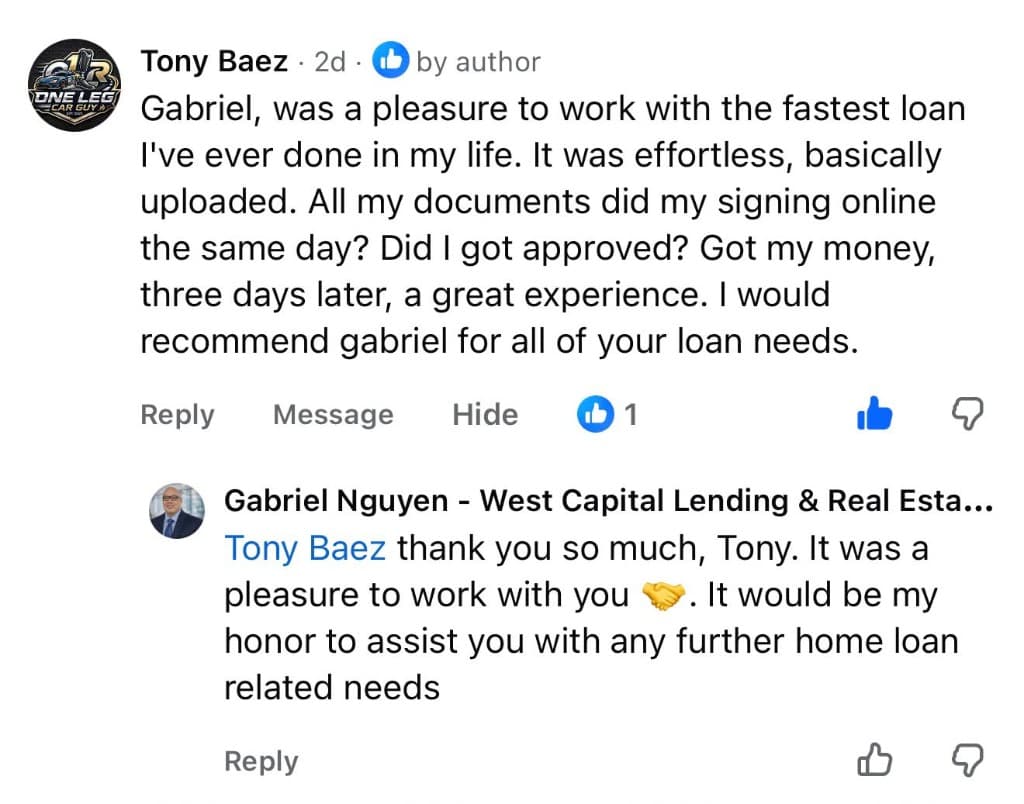
Client Messages
Real Client Experience
Genuine client messages, presented in their original form.
Market update
Today’s Mortgage Rate Environment
Stay informed with current national mortgage rate trends from Mortgage News Daily.
Mortgage rates can change throughout the day and vary based on loan type, credit profile, property, occupancy, down payment, and other factors. The rates shown here are intended to provide general market context.
Your Purchase. Your Goals. A Mortgage Strategy Built Around You.
I'm Gabriel Nguyen.
I have more than 10 years of mortgage experience and have helped fund over $100 million in mortgage loans.
I work with multiple lending sources, stay involved in reviewing your financing needs, and explain the numbers in plain language so you can decide how to proceed.
If a program may fit, I'll tell you what it would take. If I don't see a realistic path, I'll tell you that too.
West Capital Lending | Company NMLS #1566096
Let's Talk About Your Purchase.
Tell me where you are in the buying process and what you're looking to accomplish. I'll help you understand the financing options that may fit your situation and what it would take to move forward.
Gabriel Duc Nguyen Mortgage Broker NMLS #1463508
No obligation. This is a preliminary conversation, not a loan application.
Financing options and eligibility depend on your individual circumstances and lender requirements.
Frequently Asked Questions
Pre-approval can help you understand a possible price range and what documentation lenders may require before you write an offer. It is a separate step from this preliminary inquiry. Timing depends on your purchase plans, the market you are buying in, and whether a seller or agent expects a pre-approval letter.